Rajasthan Vishwakarma Yuva Udyami Protsahan Yojana (VYUPY)
Rajasthan’s Vishwakarma Yuva Udyami Protsahan Yojana supports eligible young entrepreneurs setting up or developing businesses in the state. Start by reviewing the applicant, enterprise and project conditions. Then check the loan and subsidy requirements before making a financial commitment.
SEND YOUR QUERY
Rajasthan Vishwakarma Yuva Udyami Protsahan Yojana (VYUPY)
This guide covers the main stages of a VYUPY project review:
- Scheme overview and purpose.
- Applicant and enterprise eligibility.
- Loan limits, interest assistance and margin money.
- Application sequence and lender appraisal.
- Documents to prepare before applying.
- Conditions, exclusions and questions to discuss.
What is the Vishwakarma Yuva Udyami Protsahan Yojana (VYUPY)?
Overview of the VYUPY scheme
Vishwakarma Yuva Udyami Protsahan Yojana supports eligible micro and small manufacturing and service enterprises established in Rajasthan. It covers new enterprises and eligible expansion, diversification or modernisation, subject to the notification and implementation guidelines.
The notification was digitally signed on 3 September 2025 and specifies an operative period ending 31 March 2029. The administrative department is Rajasthan’s Industries and Commerce Department; District Industries and Commerce Centres handle implementation, with the Commissioner’s office as the state nodal agency.
Interest subsidy and margin-money assistance are conditional benefits linked to the approved loan and scheme requirements. Bank appraisal and departmental recommendation remain separate steps.
Official VYUPY notification, clauses 2, 3, 6 and 13. Check the current guidelines and any later amendment before applying.
What is the eligibility creteria of the Vishwakarma Yuva Udyami Protsahan Yojana (VYUPY)?
Age, ownership and enterprise eligibility
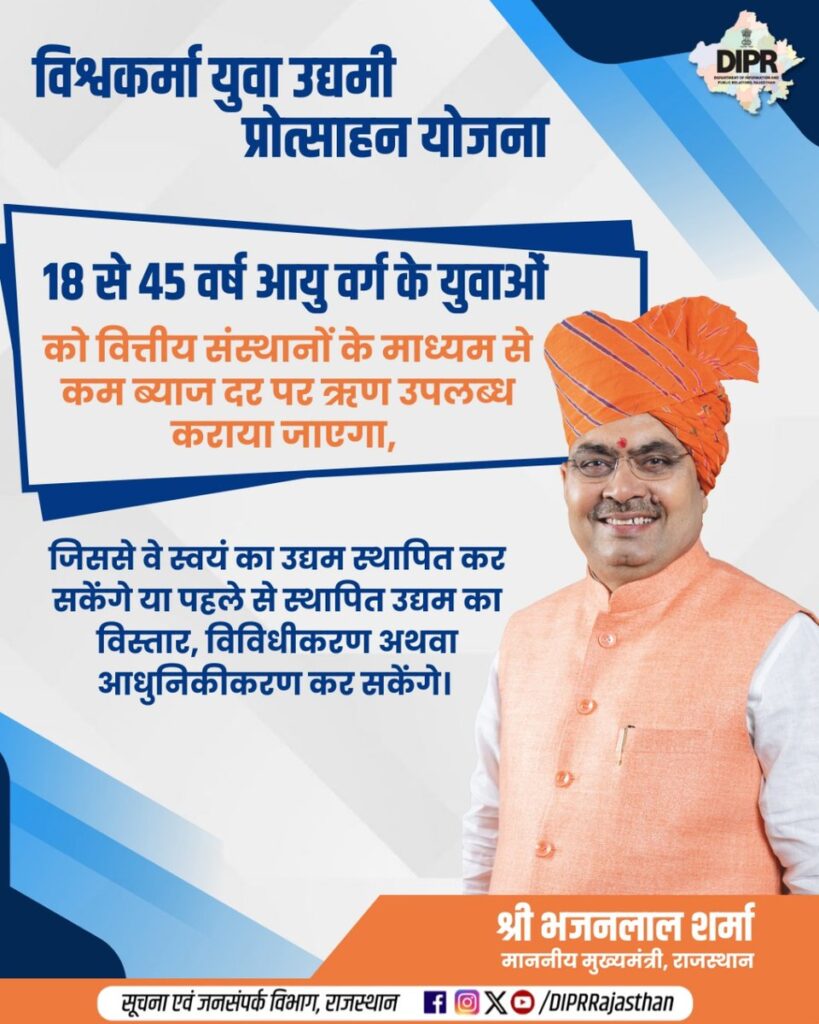
- Individual applicants must be aged 18 to 45.
- For the institutional categories listed in clause 4(ii), at least 51% ownership must be held by persons aged 18 to 45; registration must comply with the applicable rules.
- The enterprise must qualify as micro or small under the Government of India definition applicable on the application date, in an eligible manufacturing or service activity.
- Review the family/director and prior-benefit restrictions in clause 4, rather than considering a new company automatically eligible.
Earlier capital or interest assistance within the preceding five years, lender default and excluded activities need a separate check. Review the full notification and guideline conditions for the proposed applicant and project.
Not eligible
The applicant or enterprises will not be eligible under the scheme in the following circumstances:
Defaulters: Applicants who are defaulters or guilty in any financial institution/bank.
Prior Subsidies: The beneficiary unit is not eligible if it has availed of any capital subsidy or interest subsidy under any Central or State Government scheme in the preceding 5 years for the benefit received component.
What are the key benefits of Vishwakarma Yuva Udyami Protsahan Yojana (VYUPY)?
Loan limits and eligible financing
The notified maximum loan is ₹2 crore for eligible new projects or expansion, diversification and modernisation. It is a ceiling, not a promise of sanction. The applicant must contribute at least 10% of project cost.
Clause 7 distinguishes a composite loan from a term loan. Working capital is eligible as a cash-credit limit; the working-capital share of a composite loan is capped at 30%. Interest-subsidy eligibility for land and building is limited to the prescribed share, up to 25% of the loan, subject to the notification’s valuation and project conditions.
Subsidy is linked to the initially approved loan amount based on the submitted project report; a later lender-level increase does not automatically qualify. Disclose the use of funds and confirm each eligible component with the lender and department.
Interest subsidy:
Sr. No. | Maximum Loan Amount | General Interest Subsidy |
|---|---|---|
1. | Upto 1 Crore | 8% |
2. | Above ₹1 Crore and up to ₹2 Crore | 7% |
Additional Interest Subsidy (1%):
Additional 1% subsidy of interest will be available on loans above ₹1 Crore to ₹2 Crore categories like as under:
Women applicant, SC/ST, and Persons with Benchmark Disabilities entrepreneurs.
Enterprises established in rural areas.
Weavers holding a Weaver Card.
Artisans/Craftsmen holding an Artisan/Shilpi Card.
Note: If the financial institution’s interest rate is equal to or less than the subsidy rate mentioned above, 100% interest subsidy will be provided.
Margin Money Subsidy
Subsidy Amount: A margin money subsidy will be provided, amounting to 25% of the loan provided by the financial institution, or ₹5 Lakh, whichever is less.
Adjustment and release conditions: Clause 7 provides margin money of 25% of the loan or ₹5 lakh, whichever is lower, subject to the borrower having repaid an equivalent or greater amount of the loan. The assistance is held as a short-term deposit; neither the lender nor the State pays interest on that deposit, and the lender does not charge loan interest on an equivalent amount. After three years of operation without default, departmental verification and an adjustment order are required before it is credited to the loan account. If the enterprise does not operate for three years, the notification provides for return of the full margin-money amount to the department.
Source: official VYUPY notification, clause 7 (interest and margin-money provisions). The notification and current sanction conditions govern the case.
Implementation and nodal departments
- Administrative department: Rajasthan’s Industries and Commerce Department administers VYUPY.
- District implementation: District Industries and Commerce Centres handle implementation in their districts.
- State coordination: The Commissioner’s office acts as the state nodal agency and oversees implementation.
- Guidance: Consult the department’s current instructions for interpretation, implementation and monitoring.
How can you get the benefits under Vishwakarma Yuva Udyami Protsahan Yojana (VYUPY)?
Process for apply under VYUPY:
Loan eligibility:
The financial institutions which loans are eligible for get benefits under VYUPY are Schedule Commercial Banks, Private Banks, small financial bank, Regional Rural Banks (RRBs), Rajasthan Financial Corporation (RFC), SIDBI, and other Cooperative Banks.
Application Process
Application: The scheme will be implemented through an online portal.
Scrutiny of the application: A District Level Task Force Committee (DLTFC) will be formed for the scrutiny and examination of application forms.
Approval and Forwarding: Once the application approved by the district level task force committee, the recommendation will be forwarded to the applicant and the file will be move further to the respective bank.
Please Note: If the Loan directly sanctioned by financial institutions it will not be eligible for benefits under this scheme. DLTFC approval before loan sanction is mandatory.
What is the documents required under Vishwakarma Yuva Udyami Protsahan Yojana (VYUPY)?
The documents key documents required for get approval under the scheme Vishwakarma Yuva Udyami Protsahan Yojana (VYUPY) are as below:
Pan Card and Adhar card of the Proprietor/ partners/ directors (as the case may be)
MSME Certificate
BRN (Sanstha Aadhar)
Firm registration certificate
Partnership deed (in case of partnership firm)
Certificate of incorporation with MOA & AOA (in case of company)
Project report
Photos of applicant
Other documents as per requirement
OTHER TERMS & CONDITIONS:
Conditions for Beneficiaries
Proper Use of Loan: The sanctioned loan amount under the scheme must be used only for the purpose for which it was sanctioned for.
Subsidy Period: The maximum period for interest subsidy under the scheme will be 5 years from the date the establishment starts production/operation.
Moratorium Period: A maximum 6-month Moratorium Period on loan repayment may be granted. Interest subsidy will be payable even during this period, provided interest payments are made regularly.
NPA Regularisation: If your loan account is classified as an NPA (Non-Performing Asset) by the bank or loan sanctioning authority, but is subsequently regularised by the entrepreneur/enterprises, the interest subsidy and other benefits of the scheme for that period will become payable.
Disqualified Activities under the scheme
The following activities are not eligible for the scheme:
Manufacturing and sale of products made from meat, liquor and intoxicants.
Explosive and related materials.
Commercial transport vehicles which on-road price more than ₹15 lakh.
Agriculture and allied related activities which also includes animal husbandry, poultry and fisheries.
Mining and real estate related activities.
Activities operated by non-profit organisations like any NGOs, Trusts etc.
FAQs
VYUPY Rajasthan: Frequently Asked Questions
Who should request a VYUPY eligibility review in Rajasthan?
Share the proposed Rajasthan business activity, project location, applicant or entity details and whether the project is new or an expansion. Check these against the applicable scheme notification, exclusions and any later amendments before applying.
What loan amount and subsidy can my VYUPY project receive?
The scheme ceiling is not an entitlement to that amount. Review eligible project costs, the applicable loan and subsidy limits, applicant contribution and the lender’s appraisal together. Obtain a project-specific calculation before borrowing.
Is margin money subsidy paid directly to the applicant?
Do not treat a subsidy as an immediate cash payment. Confirm how it is held and adjusted, the operating and repayment conditions, inspection requirements and any recovery provisions under the applicable notification and sanction terms.
Can an existing bank loan automatically receive VYUPY benefits?
Do not assume that loan sanction alone establishes scheme eligibility. Confirm the application sequence, required departmental recommendation and the lender’s role before relying on a subsidy.
Which documents should I prepare for a VYUPY consultation?
Prepare a project summary, Rajasthan location, cost estimates, financing requirement, entity records, available Udyam details and information about earlier subsidies. The final application and lender checklists depend on the case; share records through an agreed secure channel.
Can VYUPY assistance be combined with another subsidy?
Disclose previous and proposed government assistance. The same expenditure or benefit component may be subject to restrictions; review the conditions of both schemes before including combined benefits in a financial projection.
How long will VYUPY approval and loan disbursement take?
Document readiness, departmental review, lender appraisal, queries and sanction conditions affect the sequence. Consultancy does not guarantee a sanction date, loan disbursement or subsidy release.
How can LegalMan assist with a VYUPY project?
Discuss eligibility review, project-report preparation, the applicable document checklist and application follow-up. Agree the written service scope and professional fees separately from any official or lender charges.
Verify current terms in the Industries Department VYUPY notification and subsequent amendments. Discuss your VYUPY project with LegalMan.
Process to get loan under VYUPY Scheme:
Share your enquiry
First, discuss your Rajasthan project and the proposed service scope with LegalMan.
Provide project records
Next, provide the agreed records through a secure channel. Confirm the final checklist for your case.
Prepare the application
LegalMan prepares the agreed project report and application records, then shares them for your review.
Departmental review
After checking the records, submit through the applicable route. The department reviews eligibility and may request clarification.
Lender appraisal
Following the required departmental recommendation, the lender assesses the project, repayment capacity and sanction conditions.
Sanction and disbursement
Finally, the lender decides sanction and disbursement under its conditions. An application does not guarantee a loan or subsidy.